Beyond Bullion: Global Gold Mining Equities as More Profitable Way to Own Gold’s Bull Run

Central Bank Accumulation, Sticky Green-Tech Demand for Silver, & Multi-Decade Valuation Discounts Create A Historic Asymmetric Opportunity For Indian Investors
| Miners have outperformed gold – ₹1 lakh invested in Aug 2023 is worth ₹3.78 lakh in mining equities, versus ₹2.3 lakh in physical gold | GIFT City opens global access – IFSCA funds provide investors access to global mining-equity strategies and the OPI route actually allows investment amount above the LRS limits. |
| Supply can’t keep pace -Gold has more than doubled since 2023, while mined supply has grown just ~1% | Central banks are continuing to buy – 84% of reserve managers expect gold’s share to rise over five years |
| Silver faces a growing deficit – 2026 marks the sixth straight year of supply shortfall BY 46 million ounces | Miners are generating strong cash flows – FCF yields stand at 8–10% for large caps and 15–35% for mid- and small-caps at $4,500 gold |
MUMBAI, Wednesday, 16 September 2026: Rational Equity Asset Management, an institutional boutique investment firm known for its disciplined multi-bagger approach, today released a white paper – “Beyond Bullion: Why the Miners Are the More Profitable Way to Own Gold’s Bull Run” — making a compelling case that the real opportunity in the precious metals rally is not the metal itself, but the companies that mine it.
It argues that gold and silver miners could offer investors a more attractive way to participate in the ongoing rise in precious metals. With stronger balance sheets, healthy cash generation and limited new supply, miners are generating free cash flow yields in the double digits, even at flat prices. Yet, the sector continues to trade below its decade-average valuation. The paper argues that this gap is the trade. Rational Equity believes this as one of the most compelling investment opportunities of the current cycle.
The disconnect between the value of the metals and the companies that produce them could create an opportunity for mining equities to outperform the metals themselves.
What This Means for Indian Investors
For Indian investors, gold has traditionally been held through physical bullion and ETFs. However, physical metal alone lacks yield and operating leverage. By contrast, Global Gold Mining Equities offer additional benefits through capital growth, dividends and buybacks. Furthermore, Indian investors benefit from a dual compounding effect: global precious metal rallies combined with structural rupee adjustments historically enhance overall INR-denominated returns. The whitepaper positions gold mining equities as a satellite allocation alongside physical gold and gold ETFs, rather than a replacement for them. The report notes that Gold ETFs, despite record inflows, still account for only about 0.3% of India’s gold stock. This fundamental gap is structurally, the crucial opportunity available to an Indian investor, as mining equities offer upside from higher gold prices, dividends and buybacks albeit with higher equity-like volatility.
What ₹1 Lakh Would Have Made You
To evaluate real-world performance, Rational Equity tracked the returns of ₹1 lakh invested across three channels: Physical gold in India, Domestic Gold ETFs, & Offshore Gold Mining Equities
| Investment Route | Since 2023 Breakout Return | ₹1 Lakh Becomes |
| Physical Gold (24K, India) | 130% | ₹2,30,000 |
| Gold ETF (India) | 153% | ₹2,53,000 |
| Gold Mining Equities (GDX, INR-converted) | 278% | ₹3,77,000 |
Source: Rational Equity Asset Management White Paper, August 2026. (proxied by GDX (VanEck Gold Miners ETF) converted into INR terms)
Key White Paper Insights – Gold’s Re-Rating is Structural, Not Cyclical:
The paper argues that gold’s rally since 2023 reflects a fundamental shift in how the metal is viewed as a reserve asset. Central banks are increasingly reducing their reliance on the US dollar and replacing that with gold. Three factors support this trend: US government debt dynamics where publicly held debt has crossed 100% of GDP, gold supply has grown by only about 1% despite prices nearly doubling since 2023, and the PBOC’s US Treasury holdings are at their lowest since 2001 as funds move into bullion. The World Gold Council’s 2026 survey found that 84% of reserve managers expect gold’s share of global reserves to rise over the next five years, while 74% expect the dollar’s share to fall. The paper notes “Until that successor exists, gold is the default safe-haven for that reallocation.”
Silver adds a second, independent leg to the precious-metals thesis:
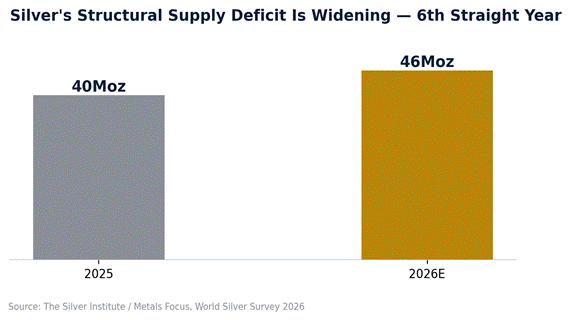
The paper also highlights silver’s strong fundamentals. 2026 is expected to mark the sixth consecutive year of a supply deficit, widening to 46 million ounces from 40 million in 2025. With nearly 74% of silver produced by product of other metals, supply cannot quickly respond to higher silver prices, supporting the case for silver.
Bull Market Reset, Not Reversal:
Gold and silver have come under pressure recently as the Iran conflict has re-escalated, pushing oil prices and US real yields higher. In June, gold ETFs saw net outflows of $8.9 billion (74 tonnes), their largest monthly redemption of the current down-cycle. ETF flows and positioning indicators confirm the structural bull market remains intact. The current environment could ultimately be supportive for gold. Rising US real yields, growing fiscal pressures and the possibility of a weaker US dollar could further strengthen gold’s role as a reserve asset. In our view, the current correction is therefore better understood as a reset within a broader bull market, rather than the start of a reversal.
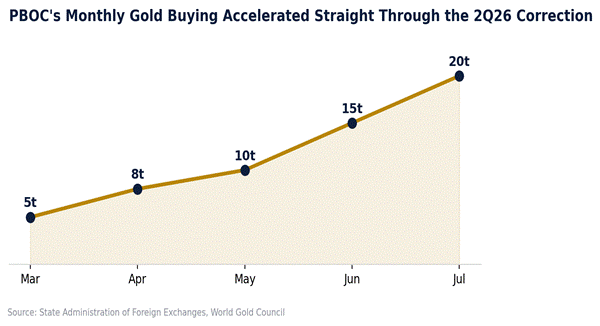
China’s central bank treated the sell-off as a buying opportunity, not a warning — its largest monthly purchase in 32 months came in July, precisely as spot gold posted its steepest monthly decline since 2008.
Miners: More Profitable Way to Trade the Metal | Where the Best Value Lies Among Miners:
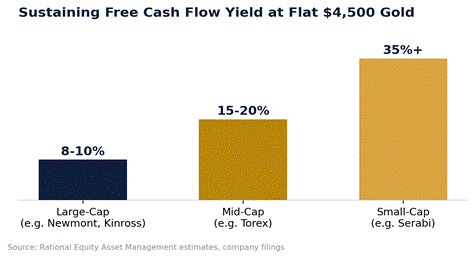
Unlike in 2013, miners today have stronger balance sheets, with many holding net cash, and generate free cash flow yields of 8–10% among large caps and 15–35% among mid- and small-caps at $4,500 gold. They are also returning more cash to shareholders through dividends and buybacks. Newmont, Kinross, Torex and Serabi, all publicly traded gold mining companies, have announced 2026 shareholder return programmes. It highlights three factors that can drive value in gold miners: Valuation, Production Growth & Stability of the country. Mid- and small-cap miners offer some of the steepest discounts, while strong production growth and stable markets such as the Americas and Australia can support higher valuations. Serabi Gold is one example, with no debt, strong growth plans and free cash flow yields of over 35%.
At a flat $4,500 gold price, mid- and small-cap producers are generating cash-flow yields the sector has historically offered only at genuine cyclical troughs — not with the metal at record highs.
Commenting on the White Paper, Vivek Iyer, Partner and CIO, Rational Equity Asset Management, said, “We see a rare combination of strong gold fundamentals and improving mining economics. We believe the bigger opportunity in this cycle is in the miners, not just the metal. Central bank demand and tight supply support gold, while healthier balance sheets, robust cash flows and growing shareholder returns make miners increasingly attractive, even as valuations remain below their long-term averages.”
GIFT City: A Gateway to Global Mining Equities
GIFT City can help Indian resident HNIs and NRIs access global gold mining investments through IFSCA-regulated funds. Investors can use structures such as feeder funds or Category III AIFs, gaining access to global managers, foreign-currency investments and a simpler route to overseas mining opportunities. Under the RBI’s Liberalised Remittance Scheme, resident Indians can now access global equity strategies — including gold and silver mining-focused funds — through vehicles structured at GIFT City’s International Financial Services Centre (IFSC) and regulated by the IFSCA.
The Bottom Line – Conclusion
The paper remains positive on both gold and silver, supported by central bank buying, supply constraints and silver’s structural deficit. But its key message is clear: the bigger opportunity may be in the miners. Stronger balance sheets, healthy cash flows and attractive valuations could allow miners to benefit more as gold and silver prices rise. we expect miners to re-rate faster than gold itself, closing the valuation gap first before a broader wave of generalist capital arrives. Gold and silver gave us the setup; the miners are where we think the money actually gets made.
(Disclaimer: The information provided here is investment advice only. Investing in the markets is subject to risks and please consult your advisor before investing)
(સ્પષ્ટતા: અત્રેથી આપવામાં આવતી તમામ પ્રકારની માહિતી કોઇપણ પ્રકારે રોકાણ/ ટ્રેડીંગ માટેની સલાહ નથી. બજારોમાં રોકાણ જોખમોને આધીન છે અને રોકાણ કરતા પહેલા કૃપા કરીને તમારા સલાહકારની સલાહ લો. વધુમાં અત્રે પ્રગટ થયેલા કોઇપણ સમાચાર કે વિગતો સાથે businessgujarat.in અંશતઃ કે સંપુર્સણપણે સહમત નથી.)