Market Valuations Reset as Earnings Momentum Builds: Bajaj Asset Management Limited
| Large and mid-cap valuations see sharp correction from 2024 peaks | BSE 500 earnings growth projected at 17% in FY27; 16% for FY28 | Credit growth picks up pace, bringing fresh sector opportunities into focus |
Mumbai, October 19, 2026: Bajaj Asset Management Limited’s latest equity market analysis points to a shift in market trends. Valuations have eased since September 2024, while earnings and credit growth are gaining momentum. However, global uncertainties and high crude oil prices could keep markets volatile in the near term.
Valuations ease, earnings expectations hold up
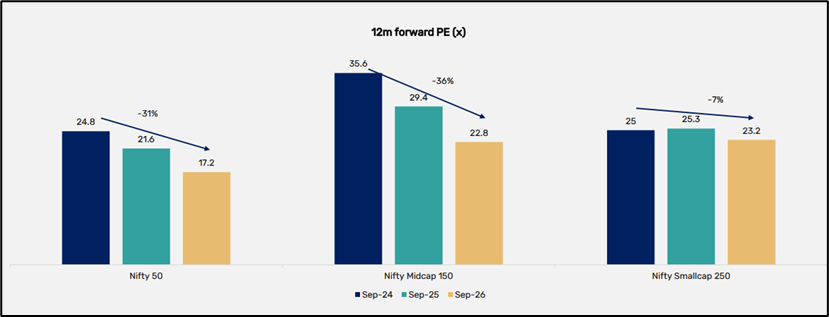
equity valuations have cooled from September 2024 levels. The Nifty 50’s 12-month forward price-to-earnings (P/E) multiple fell 31%, from 24.8x to 17.2x by September 2026. The Nifty Midcap 150 declined 36%, from 35.6x to 22.8x, while the Nifty Small cap 250 eased 7%, from 25.0x to 23.2x.
Source: MOFSL. Data as on 30th September 2026.
India’s market capitalisation-to-GDP ratio is estimated at 122% for FY27, below its September 2024 high of 150%. Yet earnings delivery remains crucial for market performance.
“Valuation multiples have eased from recent highs, but the market capitalisation-to-GDP ratio remains elevated. Sustained earnings growth will be important for market performance ahead,” said Sorbh Gupta, Head – Equity, Bajaj AMC.
The gap between prices and earnings expectations is also notable: the Nifty 50 was down 8.09% year-on-year in September 2026, even as its forward 12-month earnings per share (EPS) estimate rose 9.62%.
Corporate earnings gain momentum
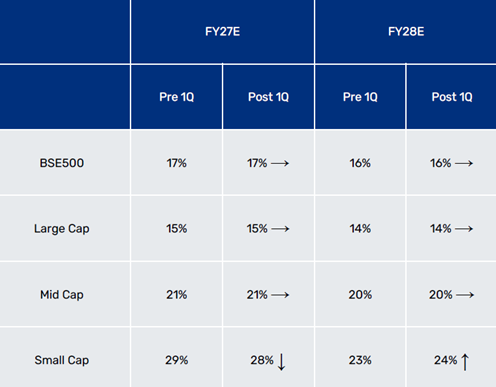
Q1FY27 earnings growth strengthened across market-cap segments. Large-cap earnings growth rose to 23% from 10% in Q4FY26, while mid-cap earnings grew 23%. Nifty 50 profits increased 19% year-on-year, with commodity and telecom companies contributing around 60% of incremental profits.
Bajaj AMC’s estimates point to BSE 500 earnings growth of 17% in FY27 and 16% in FY28. For FY27, growth is estimated at 16% for large caps, 19% for mid-caps and 28% for small caps. These are forecasts, not assured outcomes.
Source: Avendus Spark. Data pertaining to Q1FY27 released in August 2026 as per the latest available. E stands for Estimates.
Credit growth picks up pace
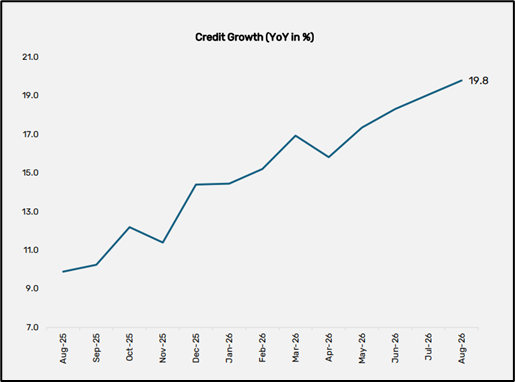
Credit growth is broadening, led by corporate and SME lending. Infrastructure financing is supporting demand from large industries. Banks have reported improving loan growth and stable asset quality, while non-banking finance companies have benefited from lower funding costs and healthy lending activity.
Source: Elara Capital, RBI. Data as on 31st August 2026 as per the latest available. FCNR is Foreign Currency Non-Resident.
Life insurers also recorded growth in the value of new business, particularly in traditional products.
“Improving credit growth and valuations support the banking outlook. Banks where loans reprice faster than deposits may be better positioned,” said Gupta.
Sector outlook: Selectivity remains key
Bajaj AMC identifies sector-specific drivers and risks rather than a uniform market opportunity:
| Banking and financial services: | Credit growth and asset quality remain supportive; margins need monitoring. |
| Healthcare: | Hospitals, diagnostics, wellness and contract research and manufacturing services benefit from long-term demand trends. |
| Power and power equipment: | Government capex, grid expansion, and sustainable-energy investment support demand. |
| Automobiles: | Volumes and affordability have improved, while raw material and currency costs may pressure margins. |
| Consumer staples: | Volume growth has improved, but pricing power and cost control remain important. |
| Information technology: | Subdued demand visibility, global policy uncertainty, and potential AI-led disruption warrant caution. |
| Pharmaceuticals: | Domestic formulations and contract manufacturing remain supportive; US generics face tariff-related risks. |
| Metals, oil and gas, and utilities: | Commodity prices, crude-related margin pressure and electricity demand are key earnings drivers. |
Outlook: Earnings delivery in focus
Geopolitical tensions, crude oil prices, US interest rates, rupee movements and foreign portfolio flows may keep near-term volatility elevated. Bajaj AMC remains focused on earnings visibility and valuations when assessing sector opportunities.
“Easing valuations and improving earnings offer a more supportive market backdrop, but global risks remain. Our focus is on selective opportunities, disciplined valuations and sustainable earnings growth,” concluded Gupta.
Source: Bajaj Asset Management Limited – Equity Market Outlook, October 2026; ECHO: Earnings, Cycles & House Outlook – Q1FY27; Motilal Oswal Financial Services Limited (MOFSL); Avendus Spark; Elara Capital; Reserve Bank of India (RBI). Data as of: September 30, 2026, unless otherwise specified. Credit growth data is as of August 31, 2026. Q1FY27 earnings data pertains to the quarter ended June 2026. FY27 and FY28 earnings growth figures are estimates and subject to change.
(Disclaimer: The information provided here is investment advice only. Investing in the markets is subject to risks and please consult your advisor before investing)
(સ્પષ્ટતા: અત્રેથી આપવામાં આવતી તમામ પ્રકારની માહિતી કોઇપણ પ્રકારે રોકાણ/ ટ્રેડીંગ માટેની સલાહ નથી. બજારોમાં રોકાણ જોખમોને આધીન છે અને રોકાણ કરતા પહેલા કૃપા કરીને તમારા સલાહકારની સલાહ લો. વધુમાં અત્રે પ્રગટ થયેલા કોઇપણ સમાચાર કે વિગતો સાથે businessgujarat.in અંશતઃ કે સંપુર્સણપણે સહમત નથી.)