PL Wealth Flags El Niño and Crude Oil Risks, Recommends Selective Equity Exposure and Accrual-Focused Debt Strategy
Strong domestic growth, returning foreign investor flows and attractive market valuations support the long-term India outlook, while inflation risks call for a staggered investment approach
Mumbai, 22nd October 2026: PL Wealth’s latest Market Outlook highlights the resilience of India’s domestic growth momentum, supported by robust economic activity, returning foreign portfolio investor (FPI) flows and a firm start to the Q1 FY27 earnings season. However, elevated crude oil prices, the risk of a strengthening El Niño, and uncertainty around global interest rates could create near-term volatility, prompting a selective approach to equities and a preference for accrual-oriented fixed-income strategies.
India’s GDP grew by 7.8% in Q1 FY27, aided by investments, as gross fixed capital formation (GFCF) grew by 11.9%. The Reserve Bank of India forecasts the GDP growth in FY27 at 6.7%. In addition, industrial activity was quite healthy, as manufacturing and service sectors grew by 9.2% and 10.0%, respectively. The non-food bank credit growth stood at 19.1% year-on-year as of July 2026.
Nevertheless, the matter of inflation continues to be an important topic of concern. The level of CPI inflation in July 2026 was recorded at 4.45%, whereas the level of food inflation was 5.52%. In addition, there is a risk of inflation breaching its projections due to increased monsoon deficit and strengthening of El Niño phenomena. As of August 26, 2026, the cumulative monsoon rainfall was 13% less than normal levels, while the planting of kharif was 2% less than the normal. Brent crude prices averaged US$90-US$93 per barrel in August 2026. In light of all these factors, PL Wealth emphasizes the potential of a 25-50 basis point policy rate increase in Q3/Q4 FY27, depending on crude oil prices and monsoon development.
Speaking on the outlook, Inderbir Jolly, CEO, PL Wealth, said: “India’s growth momentum and the return of foreign investor flows provide encouraging signals for the markets. However, elevated crude prices, monsoon-related risks and uncertainty around the global interest-rate environment call for a measured investment approach. We believe investors should remain selective, focus on quality and deploy capital in a staggered manner across investment horizons. Our long-term conviction in India remains intact, supported by domestic capital expenditure, financial deepening, demographics and structural growth opportunities.”
Equity Markets: Selectivity and Valuations Drive Positioning
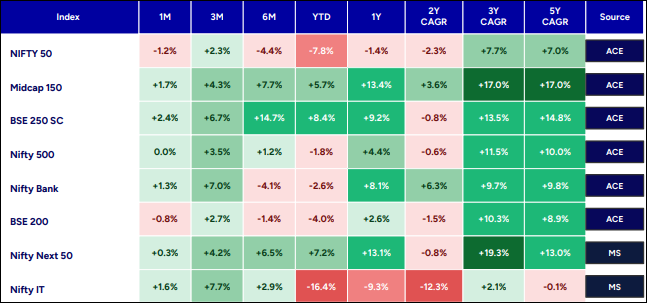
Indian equities saw contrasting results on the basis of capitalization during the month of August. Despite the continuing pressure on the Nifty 50, midcap and smallcap stocks exhibited some resilience. The Nifty 50 was trading at 24,208 on August 26, while the Nifty Midcap 150 was up 13.4% over one year on August 31, 2026, compared with a 1.4% fall in the Nifty 50.
The report states that earnings for Q1 FY27 have generally been ahead of expectations. In the universe covered by PL Research, PAT (excluding oil & gas) has grown 17% on a year-on-year basis, which is the highest growth since Q4 FY24, beating estimates by 2.6%. Sectors which posted earnings beats include banking, metals, telecom, and healthcare. High input costs might adversely impact corporate margins in the quarters ahead.
Valuations can be seen to lend some support to the medium- and long-term outlook. The Nifty was trading at 17.3 times 1-year forward earnings at 24,208, which is 11.7% lower than its 15-year average P/E multiple of 19.6 times. The base-case Nifty target by PL Research for the next 12 months is 27,123.
In the near-term, PL Wealth advises phased exposure to large and large and mid-cap strategies due to high crude oil prices and global interest rate uncertainty. In the medium-term, the report prefers exposure to large private banks, capital goods and durable consumption, along with exposure to select quality small cap, flexi-cap and multi-cap strategies. In the long-term, the positive outlook for India emanates from domestic capital spending, demographics, financial deepening, indigenous defense capabilities and growth potential.
Fixed Income: Accrual Takes Priority Over Duration
In fixed income, PL Wealth has taken a conservative approach due to changing inflationary expectations and risks related to policy rates. The RBI has kept the repo rate unchanged at 5.25% in its policy rate review in August. The closing of the FCNR deposit channel, which attracted US$100 billion, has brought additional liquidity into the banking system and stabilized the short end of the yield curve.
The report prefers the short end of the curve, especially between three months and three years, where certificates of deposit offer yields of 7.0-7.5%, and commercial papers offer 7.3-7.8%.
The five-to-eight-year duration remains tactical in nature, as the 10-year government bond yield has been anchored to about 6.72% post the August policy. The fair value estimate of the 10-year government bond yield is 6.75% – 6.90% according to PL Research, while the levels above 6.95% will present a good chance to increase the duration. But with the likelihood of a rate hike of 25 – 50 basis points in the second half of FY27, making a strong duration move at this juncture will be too hasty.
Commodities: Gold and Silver Outlook
Gold and silver continue to be sensitive to international monetary policy and geopolitical events. Gold rebounded in July, rising above US$4,100 per ounce by month end. According to PL Wealth, gold will maintain its range-bound trend for the near term, with a forecasted range of US$3,900 – 4,400 per ounce. Central bank buying is expected to support the price structure, however, changes in US monetary policy and geopolitics could increase volatility.
Silver held its range-bound trend at US$58 – 59 per ounce as of July end. While physical market deficit and demand from green technology sectors offer support to the price, a sustainable rally will require a pickup in ETF inflows.
PL Wealth’s September outlook reflects a focus on selectively participating in equities, phased capital allocation, and accrual-oriented fixed-income positioning. Though crude oil, monsoons, and international interest rates present short-term concerns, there is a positive long-term investment outlook for India based on its domestic economic strength and growth fundamentals.
(Disclaimer: The information provided here is investment advice only. Investing in the markets is subject to risks and please consult your advisor before investing)
(સ્પષ્ટતા: અત્રેથી આપવામાં આવતી તમામ પ્રકારની માહિતી કોઇપણ પ્રકારે રોકાણ/ ટ્રેડીંગ માટેની સલાહ નથી. બજારોમાં રોકાણ જોખમોને આધીન છે અને રોકાણ કરતા પહેલા કૃપા કરીને તમારા સલાહકારની સલાહ લો. વધુમાં અત્રે પ્રગટ થયેલા કોઇપણ સમાચાર કે વિગતો સાથે businessgujarat.in અંશતઃ કે સંપુર્સણપણે સહમત નથી.)