RBI has commenced the rate hike cycle, the governor indicated that “rate cuts are off the table” in the near term
MUMBAI, 7 OCTOBER: RBI chose to front load rate hike: The MPC unanimously decided to hike policy rates by 25bps to 5.5% and the stance was changed to “calibrated tightening”. With this hawkish policy pivot, RBI has commenced the rate hike cycle, the governor indicated that “rate cuts are off the table” in the near term. The governor expects deceleration in global growth and sharp acceleration in inflationary pressures which are being addressed through monetary tightening by global central banks. Despite this, domestic growth is expected to remain robust while inflation is expected to peak at 6%, but it is the second order effects which are difficult to project and hence warranted policy tightening by the RBI. We believe that narrowing interest rate differential between India and US exerted pressure on the capital account (USD 38bn depletion in forex reserves in Sep’26) which called for frontloading of rate hike and the excess liquidity in the system will narrow the growth sacrifice. (as discussed in our MPC preview note).
Optimistic on growth; liquidity tightening to continue: The RBI’s growth inflation expectations reflect optimism on domestic economic activity despite the geo-political tensions and the uncertainties around its likely impact. Growth expectations have been raised by 40bps to 7.1% in FY27, this improvement is due to steep upward revision in growth expectations in Q2FY27 (80bps, 7.2%) and Q3FY27 (40bps, 6.9%), indicating resilience in the domestic economy even as the uncertainties around the West-Asia crisis and the resultant supply disruption shows no signs of easing. Inflation is expected to peak in Q3FY27 (+1bps, 6%) before easing to 5.7% in Q4FY27. The governor highlighted that although there are some signs of elevated inflation expectations and generalisation of inflation, there is limited evidence of supply side pressures embedded in pricing behaviour. On the liquidity front, RBI will continue to tighten liquidity in the system through various tools (VRRRs, OMO and currency swaps) in this fiscal, but the surplus liquidity will reduce the growth sacrifice associated with policy tightening through rate hike. Considering the fluid macro-economic conditions, we believe that the growth-inflation projections are subject to revision which will eventually determine the appropriate monetary policy actions in the near term.
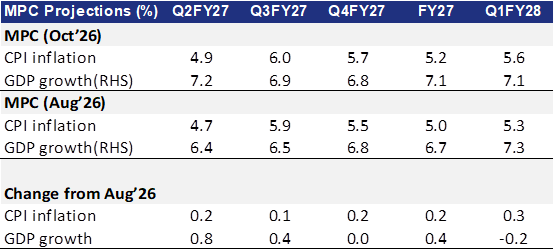
Expect a shallow rate hike cycle: Amid the difficult trade off between frontloading rate hike in response to the inflationary impact of the elevated crude oil price or to wait it out, the RBI chose the former. However, it is worth noting that the unanimous decision to hike policy rates in Oct’26 is followed by unanimous decision to maintain status quo in the previous MPC meeting in Aug’26. We believe that the policy pivot has more to do with the narrowing interest rate differential which was exerting pressure on the currency through sharp depletion in forex reserves (USD 38bn in Sep’26) while the domestic growth inflation dynamics did not warrant an immediate policy tightening. Global uncertainties continued to weigh on the domestic equity markets, benchmark yields hardened (4bps, 7.24%) while the strengthening US Dollar weighed on the INR – which we expect is heading towards 97-97.5/USD. We expect the rate hike cycle to be shallow and will heavily depend on the trajectory of crude oil price.
note from Hitesh Suvarna, Economist at JM Financial
(Disclaimer: The information provided here is investment advice only. Investing in the markets is subject to risks and please consult your advisor before investing)
(સ્પષ્ટતા: અત્રેથી આપવામાં આવતી તમામ પ્રકારની માહિતી કોઇપણ પ્રકારે રોકાણ/ ટ્રેડીંગ માટેની સલાહ નથી. બજારોમાં રોકાણ જોખમોને આધીન છે અને રોકાણ કરતા પહેલા કૃપા કરીને તમારા સલાહકારની સલાહ લો. વધુમાં અત્રે પ્રગટ થયેલા કોઇપણ સમાચાર કે વિગતો સાથે businessgujarat.in અંશતઃ કે સંપુર્સણપણે સહમત નથી.)